Terminal Value Myth 5: The Terminal value ate my DCF!
Evaluation and Summary
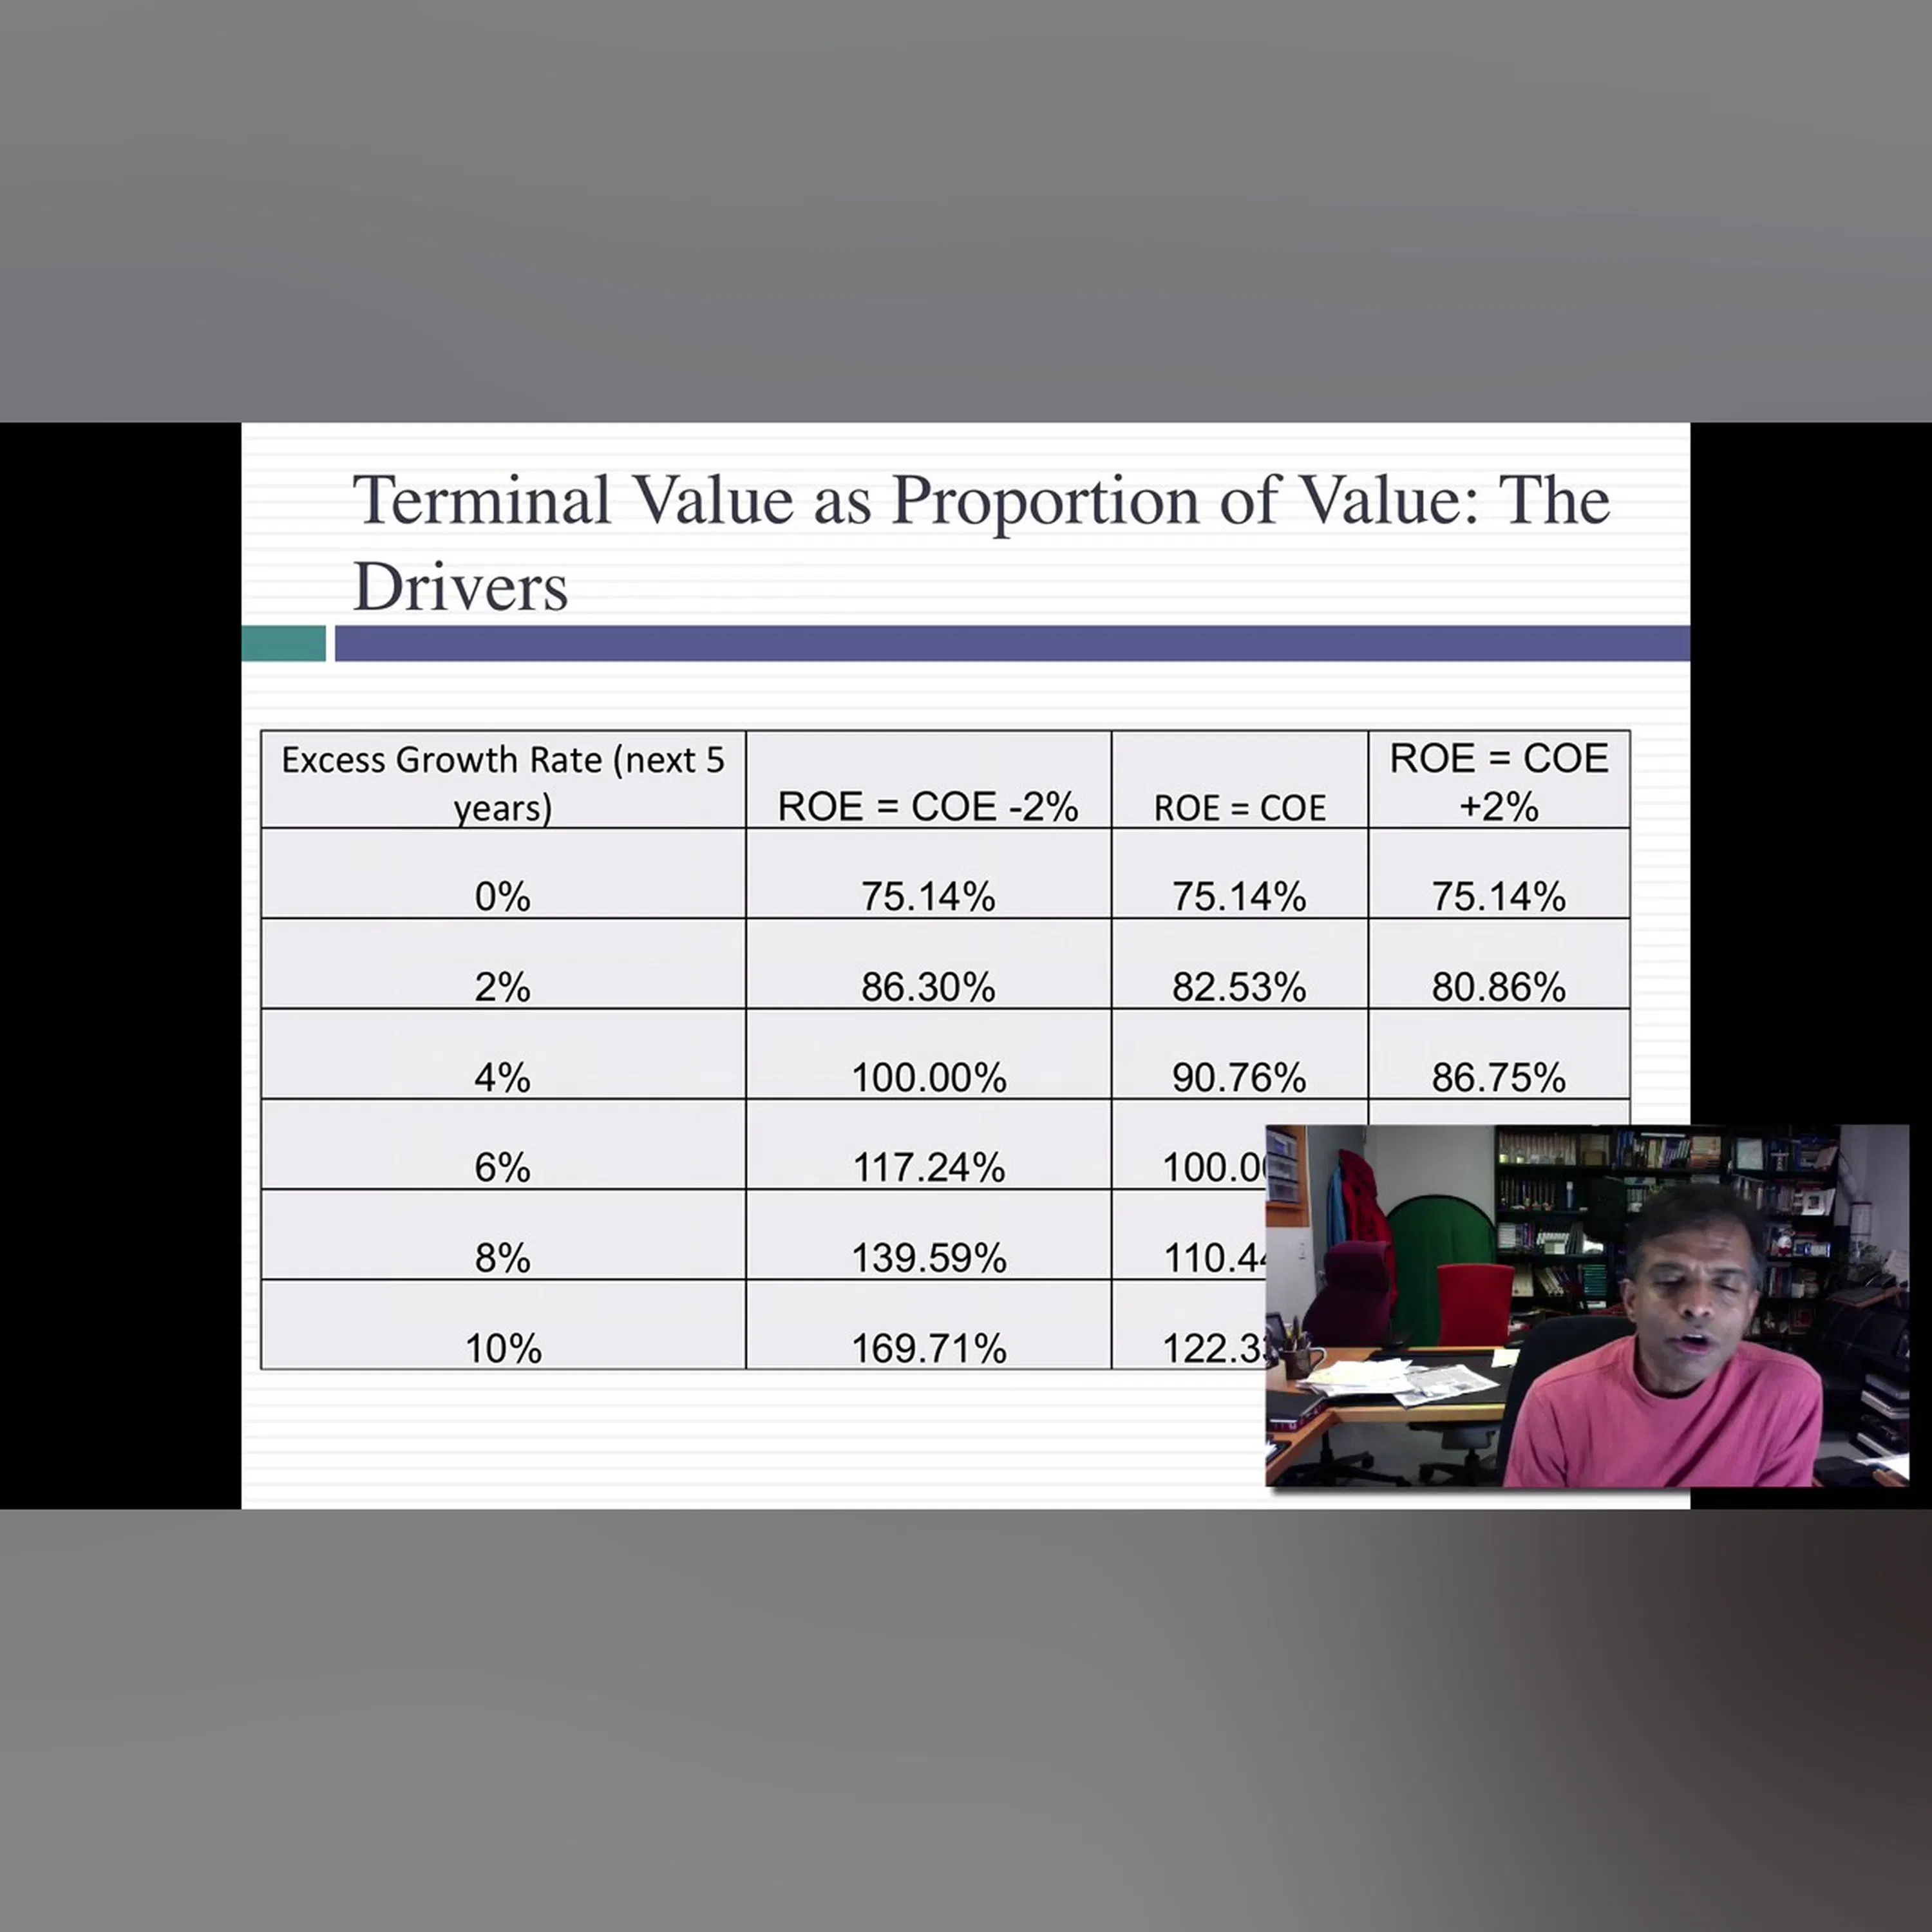
Aswath Damodaran, a renowned valuation expert from NYU Stern, addresses a common misconception about discounted cash flow (DCF) analysis in this 12-minute episode. The core myth he tackles is that terminal value—the estimated value of a business beyond the explicit forecast period—represents a problematic flaw in DCF modeling because it typically accounts for a large proportion of total valuation. Some investors view this high proportion as a reason to distrust DCF entirely, while others use it as justification to be careless about near-term growth assumptions. Damodaran argues both positions are wrong. He reframes terminal value by drawing an analogy to stock investing: terminal value functions like capital gains (price appreciation), while the explicit forecast period represents dividend income. This perspective helps explain why terminal value naturally comprises a significant portion of value in a DCF model. The episode's key insight is that although terminal value represents a large proportion of total value, it is not independent of earlier assumptions. Rather, it is heavily influenced by the growth assumptions made during the explicit forecast period—both the level of growth and the efficiency with which that growth is achieved. This means investors cannot simply dismiss near-term assumptions as unimportant just because terminal value dominates the valuation. Damodaran provides supporting materials including slides and a detailed blog post that expand on these concepts. The episode appears to be part of a series debunking myths about terminal value in DCF analysis, suggesting a systematic approach to addressing common valuation misconceptions. The presentation is concise and focused, targeting investors and analysts who use or are skeptical of DCF models. The episode aims to clarify the relationship between explicit forecast period assumptions and terminal value calculations, helping listeners understand that rigorous near-term forecasting remains critical even when terminal value comprises the bulk of valuation.
Verdict: A sharp, credible expert delivers a focused conceptual correction to a widespread valuation misconception in a tight format, though the show notes suggest limited concrete examples or step-by-step guidance.
Business rubric
-
Actionable takeaways 3/5 20%
Listeners learn to reframe terminal value as analogous to capital gains and understand its dependence on growth assumptions, but specific modeling steps or frameworks are not detailed in the show notes.
-
Evidence over hype 3/5 20%
Damodaran uses conceptual analogies (terminal value as capital gains) and references supporting slides and a blog post, but the show notes do not detail specific data, case studies or numerical examples.
-
Guest and host credibility 5/5 15%
Aswath Damodaran is a globally recognized valuation expert and professor at NYU Stern with decades of direct experience in DCF analysis and corporate finance.
-
Substance 3/5 15%
The episode addresses a focused conceptual issue with clear logic, but at 12 minutes with limited detail in show notes, depth is constrained; supplementary materials (slides, blog) suggest fuller treatment exists elsewhere.
-
Delivers on its title 5/5 15%
The title promises to address the myth that terminal value 'ate' DCF, and the episode directly confronts this misconception with a clear reframing.
-
Value for time 4/5 15%
A 12-minute episode on a focused valuation concept is reasonably paced; the brevity suits the topic, though listeners may need to consult slides and blog for full depth.
Worth it if you use DCF models, are skeptical of their terminal value component, or want to understand why near-term forecasting assumptions matter even when terminal value dominates valuation.
Based on the episode description. AI-generated; it can be wrong.
Show notes
More from Aswath Damodaran

This is Session 23 from Aswath Damodaran's valuation course at NYU Stern, focusing on real options in corporate finance. The episode covers three interconnected topics: (1) the option to expand, where companies make upfront investments that appear unprofitable in isolation but are justified by the ability to enter or…
Worth it if you're a finance student, analyst, or investor seeking to understand how option theory applies to expansion decisions, financial flexibility, and valuing equity in troubled companies.

This is Session 17 of Aswath Damodaran's corporate finance course, focusing on the capital structure decision—specifically the trade-off between debt and equity financing. The episode begins by establishing foundational distinctions: debt as fixed claims with no control rights versus equity as residual claims with…
Worth it if you're a finance student, corporate strategist, or investor seeking to understand how companies should balance debt and equity financing across different contexts and life stages.

This is a 59-minute session from Aswath Damodaran's valuation course at NYU Stern, focusing on real options theory—specifically the option to delay. Damodaran applies this financial concept to practical valuation problems, particularly patents and undeveloped natural resource reserves. The episode appears to be a…
Worth it if you're a finance professional, investor, or student needing to value patents, natural resources, or any asset with embedded optionality.

This is Session 19 from Aswath Damodaran's valuation course at NYU Stern, focusing on the foundational concepts of pricing companies. The episode distinguishes between the pricing process and the intrinsic value process, establishing why pricing (using multiples) is far more prevalent in practice than fundamental…
Worth it if you're a serious investor or student building foundational knowledge in relative valuation and want to learn from one of the field's leading educators.

Aswath Damodaran, a renowned valuation professor at NYU Stern, tackles a common misconception in financial modeling: the belief that discounted cash flow (DCF) analysis cannot accommodate negative growth rates. The episode challenges the myth that perpetual growth models break down when companies face declining…
Worth it if you're a financial analyst, investor, or student of valuation who wants to challenge assumptions about DCF modeling and improve your ability to value declining or mature businesses.

This is Session 18 from Aswath Damodaran's corporate finance course at NYU Stern, focusing on optimizing a company's financing mix—the balance between debt and equity. The episode builds on previous discussions of the debt trade-off by incorporating agency costs and financial flexibility into the analysis. Damodaran…
Worth it if you're studying corporate finance, need to understand debt-equity optimization for your role, or want to learn from one of the field's best teachers.